PAYNETHE WEEKLY JOURNALNOVEMBER 6, 2026
PAYNE
INDEPENDENT PERSPECTIVE · THE BAY AREA & BEYOND
VOL. I · NO. 14FRIDAY, NOVEMBER 6, 2026BY PAYNE SHARPLEY
WALL STREET MEETS YOUR STREET

The wealth effect
works both ways.

Stocks retreat. Housing rules change. The future keeps arriving.
What it means for Bay Area buyers, sellers and operators.

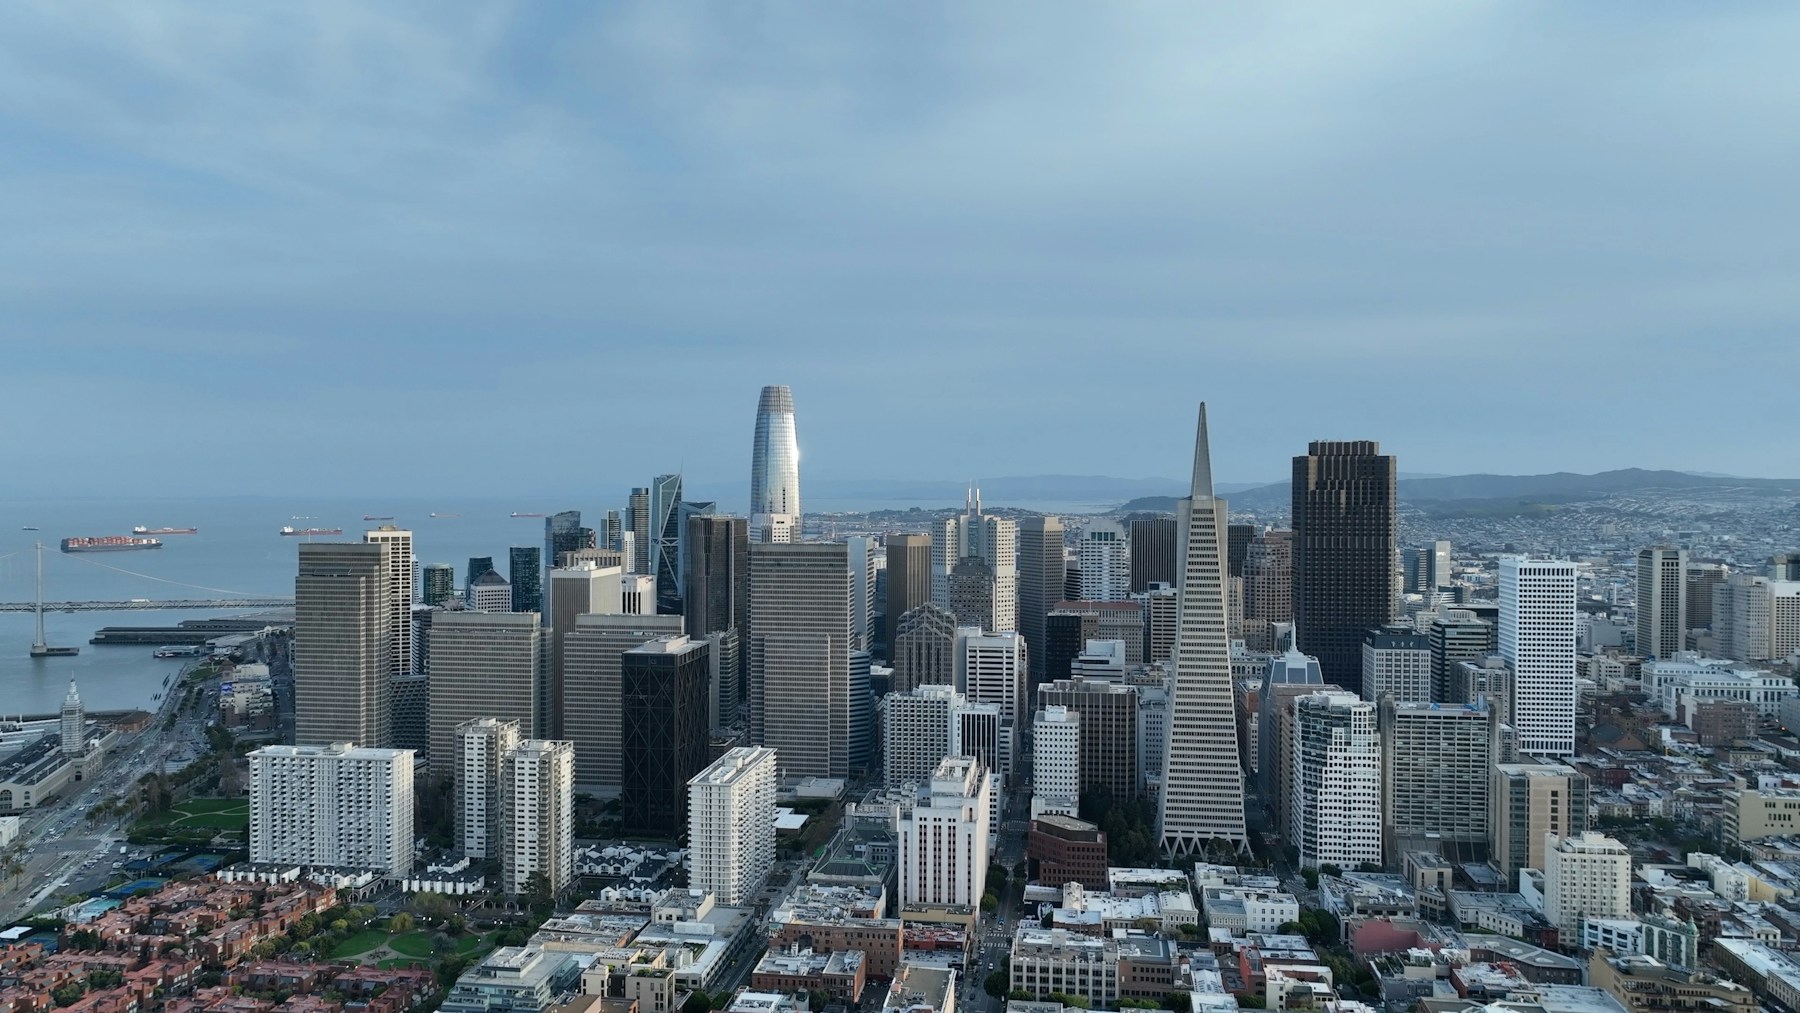
San Francisco’s financial district. Photograph: Nathan Barteau / Unsplash.
NASDAQ COMPOSITE−5.5%NOV. 5 · APPROX.
S&P 500−4.4%NOV. 5 · APPROX.
30-YEAR MORTGAGE7.18%FREDDIE MAC · NOV. 5
MARKETS / 03

Bubble or correction?

The spending, cash flow and valuation behind the selloff.

HOUSING / 05

What the vote changed

Housing finance, local measures and Wiener’s transit policies.

THE FUTURE / 08

Already science fiction

Neuralink’s research frontier. Citis Agent’s practical ambition.

PAYNETHE EDITOR’S DESKNOVEMBER 6, 2026
IN THIS ISSUE

Follow the money.
Then follow the land.

A guide to the forces changing the next real estate decision.

Wall Street is marking down the price of the future. Bay Area voters are deciding where that future can be built. And the technology itself keeps moving forward.

This week, those three stories collided. For a homeowner, the connection runs through a buyer’s stock portfolio, the cost of a mortgage, the rules governing a nearby parcel, and the confidence to make a commitment.

This edition follows those connections, separating the numbers we can observe from the scenarios we still need to test.

A stock-market correction is a signal to reassess. It is not an appraisal of your home.

Payne Sharpley
REALTOR® · INTERO

ABOUT THIS EDITION

Reporting cutoff: November 5, 2026. Election counts are dated and preliminary unless a race call is noted. Sources are linked throughout. Photographs provide geographic or technology context, not images of the reported events.

PAYNEMARKETS / THE SELL-OFFNOVEMBER 6, 2026
01 / THE COVER STORY

The bill arrives before
the payoff.

A correction in prices. A harder question about the economics of AI.

Our assessment: a significant repricing of AI investment expectations, with bubble-deflation risk in the most exposed businesses. There is not enough evidence to declare either a durable bottom or the collapse of the entire AI economy. A correction describes the size of a decline; a bubble diagnosis concerns the assumptions embedded in prices. Both can be true in different parts of the same market.

The closing scoreboard

IndicatorNovember 5 observationWhat it tells us
Nasdaq CompositeApproximately −5.5% for the daySelling concentrated in technology; the index entered correction territory, more than 10% below its recent peak.
S&P 500Approximately −4.4%The shock extended beyond a handful of speculative names.
Dow industrialsApproximately −3.4%The broader economy was also being repriced.
NvidiaApproximately −9.3%The most prominent supplier to the AI buildout was hit particularly hard.
10-year Treasury yield4.84%, versus 4.90% WednesdayGovernment bonds gained as stocks fell; this was not simply a same-day surge in benchmark borrowing costs.

Market moves: AP closing coverage. Treasury comparison: AP global market coverage. Figures are rounded; intraday quotes are not mixed into this table.

THE CASH TIMING GAP · ALPHABET Q3 2026Operating cash flow$42.3BCapital expenditures$51.4BCapex / operating cash flow: 122% · Free cash flow: −$9.1BQuarter also includes fine payment and inventory effects. Source: Alphabet Q3 earnings call.

First: the cash arrives later than the bill. Alphabet’s Q3 report showed $42.3 billion of operating cash flow, $51.4 billion of capital expenditures, and negative $9.1 billion of free cash flow. Spending equaled about 122% of operating cash flow, calculated from those figures. The quarter also included a $5.2 billion European Commission fine payment and an inventory buildup; it would be wrong to attribute the entire shortfall to recurring AI economics. Its full-year capex guidance remained $195–205 billion. Alphabet earnings call

Meta separately guided to $135–145 billion of 2026 capital expenditures, including finance-lease principal payments. Its Q3 capital spending was $34.91 billion. Meta results

These are company-wide infrastructure budgets, not clean measures of AI-only investment. Nevertheless, the financing question is concrete: how quickly do these commitments turn into cash customers actually pay? Delayed monetization can depress investment returns even if the technology works extremely well.

PAYNEMARKETS / THE NEXT MOVENOVEMBER 6, 2026
01 / CONTINUED

What makes a bounce
worth believing?

Growth, valuation and confidence do not always move together.

Second: the buildout timetable is being repriced. Reuters reported that investors were reassessing data-center expansion after the election. Political opposition can affect permitting, power availability, construction schedules and the economics of new facilities. The mechanism is more specific than “Democrats won, so stocks fell.” A slower rollout could hurt equipment suppliers while reducing spending pressure on some established technology platforms. Reuters market analysis

Third: growth and valuation are separate variables. Consider a hypothetical business earning $10 per share at a 30-times earnings multiple: its price is $300. If earnings grow 10% but investors reduce the multiple to 25, the price becomes $275—a decline of 8.3% despite higher profits. This is an illustration, not a quoted valuation for any company. Extraordinary technology does not guarantee attractive returns at every purchase price.

Fourth: concentration transmits the shock. A household can have its job, unvested compensation, invested savings and future down payment tied to the same industry. What looks diversified across several technology tickers may remain one economic exposure. In the Peninsula housing market, that overlap matters more than the color of a single trading screen.

Will the downturn continue? What would make a bounce credible?

My working view is to plan for continued volatility rather than assume an immediate recovery to the highs. That is a risk-management judgment, not a calibrated probability forecast. The evidence supports greater caution about spending and valuations; it does not establish the duration of the adjustment.

ScenarioEvidence that would strengthen itBay Area housing implication
Earnings-supported recoveryGuidance holds; cloud and AI demand translate into cash; gains broaden beyond a few stocks; financing remains available.Some deferred purchases may return as liquid wealth and confidence recover.
Volatile valuation resetBusinesses grow but spending stays heavy; shares repeatedly rebound and retreat; investors accept lower multiples.Longer deliberation and more price sensitivity, especially among equity-dependent buyers.
Deeper investment contractionOrder cancellations, reduced earnings forecasts, tighter financing, delayed offerings and weakening employment reinforce one another.Greater risk of withdrawn buyers, slower absorption and concessions. Effects would vary by neighborhood and property type.

A sharp rebound alone does not prove that the underlying economics improved. For the next issue, the useful monitoring set is earnings revisions, cash conversion, breadth of the rebound, credit spreads, IPO execution and local employment. We have not verified a current credit-spread series or a fresh local housing-transaction sample; we therefore make no claim that a financing crisis or a local price decline has already begun.

PAYNEHOUSING / THE BALLOTNOVEMBER 6, 2026
02 / POLICY & PLACE

Money. Permission.
And the land underneath.

The Bay Area housing vote is a collection of different decisions.

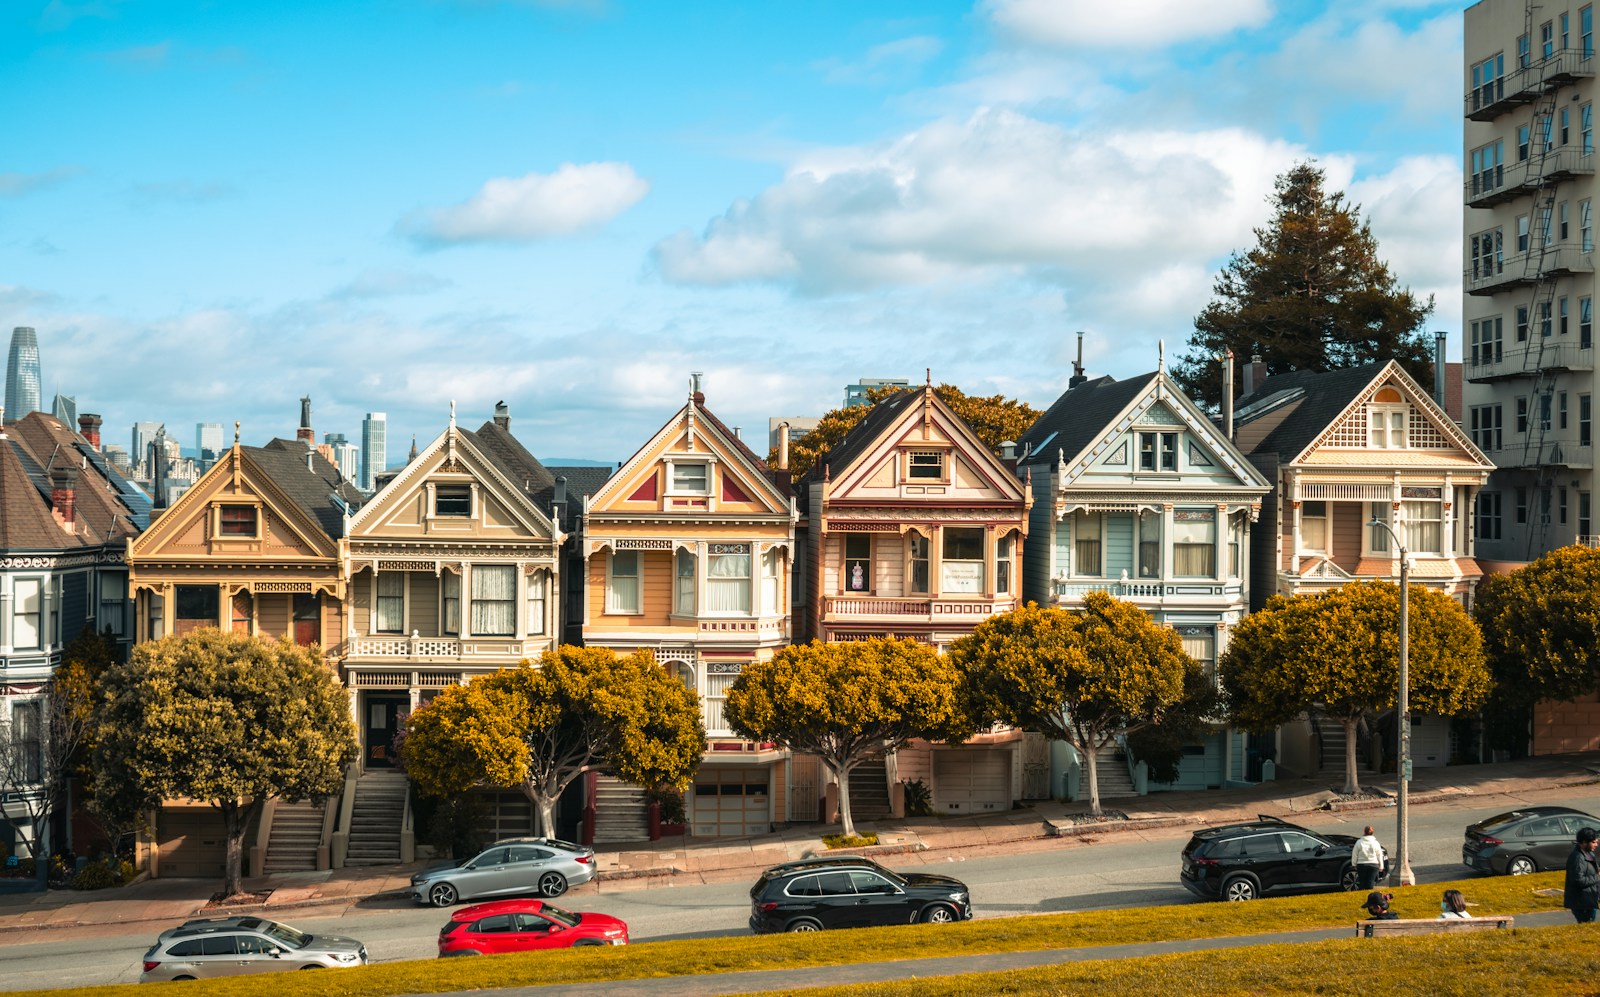
San Francisco homes. Photograph: Nikhil Mistry / Unsplash.

The most useful election question for a property owner is what changes on the ground: who can finance a purchase, where a building can be considered, and what costs remain. Statewide programs apply across the Bay Area, but their funding is not automatically allocated to any particular county.

Funding measures with reported approval

California Proposition 1: $11.25 billion in housing bonds. AP called the measure for passage. The program authorizes $10 billion for state housing programs and $1.25 billion for veterans’ home loans. Funds are allocated over time. For Bay Area affordable-housing developers, this can expand financing opportunities; it is not an immediate reduction in every homebuyer’s borrowing cost. Official fiscal analysis · Statewide results

California Proposition 37: assistance for qualified new-home buyers. AP also called this measure for passage. It authorizes up to $25 billion of revenue bonds for a CalHFA loan program, with assistance covering up to 17% of the price of qualifying newly built homes. This is repayable financing—not a universal grant for resale purchases. Eligibility, implementation and participating inventory will determine its practical reach. Official analysis · Results

San Francisco Proposition C: a larger Housing Trust Fund. Reported as approved, with about 81.1% support in the November 5 tally. The measure increases required contributions from existing General Fund revenue, beginning in fiscal 2028–29 and reaching approximately $125 million annually around fiscal 2036. It does not deliver $125 million of new construction spending tomorrow. The relevance is a more durable funding source for affordable housing and preservation. Results · Funding schedule

Regional Transit Measure: the connection between homes and jobs. VTA announced voter approval of RTM on November 4. It supports service across the five-county district, including Santa Clara County’s connections through VTA, BART and Caltrain. Transit funding is housing-adjacent: permitted density is more useful when residents can reliably reach jobs. It does not guarantee a price premium for every station-area property. VTA announcement

PAYNEHOUSING / LOCAL RULESNOVEMBER 6, 2026
02 / CONTINUED

One region.
Different directions.

Peninsula and Santa Clara County votes—and where Scott Wiener’s policies fit.

Peninsula and Santa Clara County: the vote was not uniform

MeasureLatest retrieved count or reported outcomeWhy an owner or developer should care
San Bruno S63.9% Yes; preliminary November 5 tallyRepeals the 1977 ordinance requiring votes for certain height, density and related changes. Removes a local constraint; does not approve every future project.
Cupertino L87.5% Yes; preliminary November 5 tallyRequires two-thirds voter approval for specified rezoning or development of designated parks and open space. This is a protection measure, not a citywide increase in residential density.
Los Altos D59.7% No; preliminary November 5 tallyThe proposed additional voter-approval restriction on downtown parking-plaza changes was losing. A defeat would preserve flexibility, not create a construction permit.
Menlo Park P53.4% No; preliminary November 5 tallyThe proposed downtown parking restriction was also losing. Existing housing proposals still face their own approvals and financing requirements.

Definitions: San Bruno’s ballot text, Cupertino’s measure explanation, Los Altos and Menlo Park measure descriptions. Counts: San Mateo County results, Santa Clara County results. These local counts are preliminary and are not certified final results.

A transaction-cost sidebar for San Francisco operators: Proposition J had 80.3% support in the retrieved tally. It would remove the foreclosure transfer-tax exemption for specified commercial and multifamily transactions; it is not a blanket new tax on ordinary single-family resales. Distressed-property underwriting needs to account for applicable transfer costs and the final effective rules. Results · Measure explanation

Where Scott Wiener’s policies fit

Wiener’s SB 79 is an existing state law, signed in 2025 and operative beginning July 1, 2026—not a proposition voters just passed. It allows qualifying transit-oriented housing on eligible residential, mixed-use and commercial sites near specified stops, with eligibility rules, local implementation options and exceptions. The regional summary identifies San Francisco, San Mateo and Santa Clara among the applicable urban transit counties. Unincorporated areas have a later implementation timetable. HCD guidance · Regional implementation summary

Wiener and Jesse Arreguín’s SB 63 created the framework for the regional transit funding vote. Together, the policies address two related problems: allowing more housing near transit and maintaining the transportation that makes those locations useful. MTC explanation

For a landowner, that means a parcel’s development potential deserves a current review. It does not mean every house within an arbitrary circle around a station can become a tower. Confirm the stop classification, parcel eligibility, applicable local plan, overlays, affordability requirements and physical constraints, then test construction cost and financing. Legal capacity and economic feasibility are separate calculations.

PAYNECAPITAL / THE HOUSEHOLDNOVEMBER 6, 2026
03–04 / RATES & THE IPO

Lower rates cannot
replace lost liquidity.

Two channels through which financial markets reach the front door.

MONTHLY PAYMENT RELIEF$41

Illustration: $1M loan, 7.24% → 7.18%.

STOCK DOWN-PAYMENT LOSS$60,000

Illustration: $600,000 portfolio falls 10%.

Rates down.
Wealth down.

Freddie Mac’s November 5 survey put the average 30-year fixed mortgage at 7.18%, down from 7.24% a week earlier. This is a weekly national measure, not an individual jumbo-loan quote or a complete reading of Thursday’s trading. Freddie Mac release

On a hypothetical $1 million, 30-year fully amortizing loan, the change reduces monthly principal and interest from approximately $6,815 to $6,774: about $41. Taxes, insurance, points and other fees are excluded.

Now compare a different illustration: a buyer earmarks a $600,000 stock portfolio for a down payment. A 10% decline reduces its value by $60,000 before tax considerations. If that portfolio supplies the entire down payment and the buyer maintains a fixed 20% down-payment ratio, the implied purchase budget falls from $3 million to $2.7 million. This isolates the down-payment constraint; lender qualification, reserves, other assets and willingness to borrow can change the outcome.

That contrast explains why modest rate relief may not offset a major equity shock for some buyers. The first change affects the monthly payment; the second can affect whether the transaction can close at all.

The IPO
stress test.

Anthropic’s filing put a potentially enormous offering on the calendar, but final valuation and execution remain unsettled. AP’s filing coverage describes substantial financing needs and an uncertain market backdrop. AP IPO report

For housing, the relevant sequence is ownership, permitted liquidity, taxes, available cash and an actual purchase decision. A company valuation is not an employee’s checking balance. An expected IPO should not be treated as guaranteed financing for a home purchase.

A recovery in public technology shares could improve the backdrop for an offering and household confidence. Further weakness could change valuation expectations or timing. Those are scenarios, not a report that Anthropic has postponed its offering. No postponement is asserted here.

The local market will not receive any proceeds evenly. Employee geography, existing homeownership, family preferences and sale restrictions influence where demand emerges. Watch actual offering terms and completed transactions rather than translating a company valuation directly into a forecast for Palo Alto home prices.

PAYNETECHNOLOGY / THE FRONTIERNOVEMBER 6, 2026
05 / THE FUTURE IS HERE

Already living
in science fiction.

Brain interfaces are moving from movie premise to clinical research.

Electronic circuitry, contextual image—not a Neuralink implant. Akshat Sharma / Unsplash.
TELEPATHY

Thought → device

Investigational device control for people with paralysis.

BLINDSIGHT

Stimulation → perception

Visual-prosthesis research, not a consumer launch.

Controlling a computer through a brain implant used to sound like a movie premise. Now it is part of clinical research. The extraordinary part is real; so are the distinctions between a demonstration, an investigational device and a broadly available medical product.

Telepathy is Neuralink’s device-control program, intended to let people with paralysis interact with computers through brain signals. Blindsight is its visual-prosthesis development program, intended to generate visual perception by stimulating relevant brain regions. Neuralink describes its devices as investigational and not approved for general commercial use. These are two product directions—not two newly approved consumer launches. Telepathy · Blindsight

The fresh news hook is Musk’s October 30 update, reported November 1, claiming Blindsight was ready from an engineering standpoint and awaiting regulatory approval. That is a founder’s statement about readiness, not clinical proof that the device restores normal sight. Announcement reporting

Meanwhile, METR’s November 5 assessment estimated that Anthropic’s internal benchmark progress accelerated about 1.9 times relative to its earlier pace. It reported substantial uncertainty, limitations in attributing progress to AI, and redactions of important evidence. Faster benchmark progress does not translate directly into the same productivity gain in every occupation. METR’s assessment

PAYNETECHNOLOGY / THE OPERATORNOVEMBER 6, 2026
05 / FROM THE FOUNDER

Meet the idea
behind Citis Agent.

A connected operating system for real estate operators.

01Know the contextContacts · properties · documents
02Coordinate the workMarketing · CRM · analysis
03Record the outcomeOwners · follow-up · daily brief
Proposed workflow · Development and pilot stage · Not a screenshot of a released product

The practical AI opportunity is less theatrical but closer to daily revenue: extracting a deadline from a document, reconciling a property’s records, preparing a follow-up with the right context, or identifying a missing assumption before it enters an underwriting decision. Each output still needs reliable sources and a defined review process. A polished summary of the wrong document is not useful automation.

From the editor: introducing the direction behind Citis Agent. I am building Citis, and this is an update on our own work. Citis Agent is the connected operating system we are developing for real estate operators: one place to organize the operator’s criteria, property and deal history, relationships, documents, tasks and decisions across authorized tools.

The first workflow we are shaping connects marketing, CRM, analysis and coordination. Imagine a contact engaging with a property campaign and replying to an email. With the necessary systems connected, the intended workflow identifies the relationship, checks existing follow-up, prepares a relevant next step, assigns responsibility and records the outcome. A daily brief shows what needs attention, what was completed and what remains unresolved.

The broader roadmap includes sourcing, underwriting, entitlement research, accounting and investor reporting. Those capabilities depend on validated data and integrations; this is a development and pilot-stage introduction, not a claim that every connection or workflow is already shipping.

For an operator, the promise worth testing is straightforward: less time reconstructing context, fewer missed commitments and more accountable execution. We will measure actual time saved and completed follow-ups rather than confuse a generated message with a business result.
Less time reconstructing context.
Fewer missed commitments.

Interested in discussing a pilot? Email Payne or send a text.

PAYNEREAL ESTATE / THE PLAYBOOKNOVEMBER 6, 2026
06 / THE PRACTICAL VIEW

Make the next move
with better evidence.

For buyers, sellers and operators navigating a noisier market.

For sellers: use recent closed comparables alongside current competing inventory and actual showing-to-offer conversion. Ask how a buyer plans to fund the purchase, not just whether the offer says “cash.” Monitor qualified tours, disclosure requests, offers and withdrawals over a defined period. A weak stock-market day alone is not a reason for an arbitrary price cut; a sustained deterioration in relevant buyer response is evidence to revisit positioning.

For buyers: distinguish long-term affordability from the hope of catching the bottom. Recalculate liquid funds, lender requirements and reserves before bidding. In a stock-funded purchase, the ability to close should not depend on a hoped-for rebound. If competition eases, that may improve the room to investigate condition, obtain financing and negotiate terms—but a desirable, scarce home may still attract multiple buyers.

For developers and operators: update the parcel’s legal potential and the project’s financial assumptions separately. More permitted density can improve options while expensive financing or slow absorption reduces the price a project can support. Test lower exit prices, longer holding periods and the cost of additional capital. A new law is an input to underwriting, not a substitute for it.

The next useful evidence is local: new pendings, cancellations, price reductions, days to contract and concessions, separated by city, price band and property type. Until that evidence arrives, the honest conclusion is that the risk environment has changed—not that every Bay Area home has already lost the same percentage as the Nasdaq.

WATCH LOCALLY

New pendings · Cancellations · Price reductions · Days to contract · Concessions
Compare by city, price band and property type.

Photography & sources

San Francisco skyline: Nathan Barteau. Housing: Nikhil Mistry. Circuitry: Akshat Sharma. Photographs via Unsplash. Financial, legislative and research sources are linked alongside the reporting.

Payne Sharpley · REALTOR® · CalRE #02195155 · Intero Real Estate Services 650.384.3546 · payne@paynesoldit.com · PAYNE archive

Analysis and illustrations are informational, not individualized investment, tax, legal or lending advice. Legislative summaries do not establish parcel eligibility. Rates and election counts are dated observations. Citis is the editor’s own venture; its described operating-system workflows are in development. Equal Housing Opportunity.